US economic policy: what to watch for over the next two years after the midterm elections?
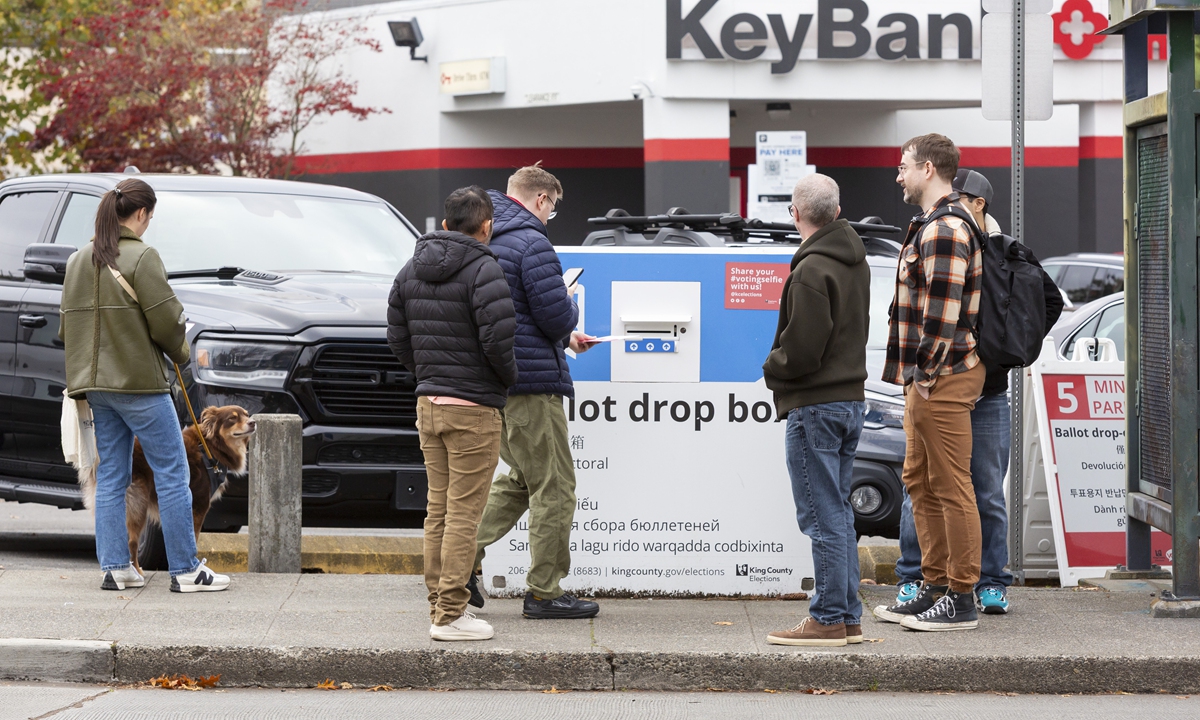
Americans cast their ballots at an early voting station in Seattle, the US, on November 1, 2026 local time, ahead of the US midterm elections on November 3. Voters will choose all 435 members of the House of Representatives and 35 of the Senate's 100 seats. Photo: IC
The midterm elections handed the Democratic Party control of both the House and the Senate. From January 2027, the US will have divided government, with the White House and Congress controlled by different parties. This will reshape how economic policy is made over the next two years and influence global markets' assessment of US fiscal, trade and geopolitical risks.
Economically, the midterms sent two signals. The US economy still has room to grow and innovate, but the costs of inflation, fiscal strain and external conflicts are quickly turning into domestic political pressure. The White House's ability to push major legislation has narrowed sharply, though it retains significant executive authority over tariffs, regulation and foreign policy.
The midterms highlighted the gap between solid macroeconomic numbers and how households actually feel. Strong employment and corporate profits have supported growth, yet many families have not felt better off. Even before the election, the cost of living had already become a top voter concern.
The current administration has tied tariffs, manufacturing reshoring, immigration curbs and a hardline foreign policy to economic security and national interests. Yet when these measures overlap with high prices, rising business costs and energy shocks, voters ultimately judge them by their purchasing power and daily expenses. The oil-price spike from the US-Israel-Iran conflict, in particular, has made the costs of foreign policy a direct domestic economic and political issue.
The midterm outcome does not necessarily mean voters reject the goals of industrial revitalization and economic security. It does, however, underscore the economic costs of pursuing those goals. For the White House, the central task over the next two years will be to maintain the existing policy direction while responding to concerns over the cost of living, investment expectations and the quality of growth.
With Democrats now controlling both chambers of Congress, the White House will face higher negotiating costs in pushing through a new round of large-scale tax cuts, expanded spending or other policies that require legislation. The House holds key levers over appropriations and oversight, while the Senate has confirmation power over important appointments. Disputes between the two parties on fiscal policy, health-care subsidies, financial regulation and AI governance are likely to shift from differences of principle into concrete budget and legislative bargains.
Divided government does not, however, necessarily mean economic policy will grind to a halt. The president retains veto power and can still use executive orders, regulatory discretion, diplomatic negotiations and existing trade tools, such as Section 232 and Section 301 authorities. These tools are subject to congressional oversight, judicial review and market feedback, but the executive branch retains the ability to take the initiative. As a result, legislative expansion may be slow, while policy adjustments at the administrative level may become more frequent.
Going forward, changes in US economic policy are likely to affect the global economy mainly through three channels.
The first channel is trade and supply chains. The president can still use existing trade tools, but Congress will shape new authorizations, industrial subsidies and outbound investment rules. China and the US may find room for pragmatic talks, yet frictions could also arise over critical technologies, autos and mineral supply chains. A full rollback of tariffs is unrealistic for US allies, and cross-border firms will continue to face the costs of shifting rules and supply-chain adjustments.
The second channel is the dollar and financial markets. Fiscal talks, treasury issuance expectations, inflation trends and Fed policy will together drive US yields and the dollar's path. Higher US policy uncertainty can quickly spill over from the bond market into the exchange rates, financing costs and capital flows of emerging economies.
The third channel is energy and geo-economics. The US-Israel war on Iran has affected oil prices, shipping and inflation expectations, showing that the costs of US foreign policy reach well beyond the battlefield and diplomacy. Some US media suggest domestic political setbacks may push the White House to focus more on foreign affairs. Yet high energy prices and war costs have also eroded support for further escalation. Rather than simply predicting whether the White House will turn more hardline, what matters is watching how energy prices, domestic pressure and diplomatic talks interact.
Although Democrats have won control of the new Congress, the new Congress will not be sworn in until January 3. This is not a power vacuum, but a transitional period. Whether new temporary funding bills, comprehensive spending agreements or arrangements on the debt ceiling and defense spending emerge will shape the starting point for fiscal policy next year.
For China and the global economy, it is important to watch trade restrictions, energy shocks and possible financial market adjustments, while also recognizing that shifts in US policy may create openings for communication and cooperation.
The author is an associate research fellow at the Institute of American Studies at the Chinese Academy of Social Sciences. opinion@globaltimes.com.cn
RELATED ARTICLES